

Private space companies are developing indigenous technologies, but scaling them requires deeper funding
The sector needs incentives, funding and new lending models to build scale
Private participation can grow alongside ISRO, but launch vehicles need tighter controls
India’s space sector is entering a phase where the question is no longer whether private companies should participate, but how far that participation should go. With hundreds of start-ups entering the sector, the government is trying to build an ecosystem that can move beyond launches and satellites to create globally competitive space businesses. But opening up the sector also raises a more difficult question that where should the state draw the line.
For the Indian Space Association, the answer lies in a division of roles rather than a retreat of the state. In an interview with Outlook Business, Lt. Gen AK Bhatt (Retd), Director General of ISpA said that ISRO will continue to retain strategic capabilities, advanced research and missions that are central to national security, while private companies can take on commercial activities and scale mature technologies.
1 September 2026
Get the latest issue of Outlook Business
“Privatisation of space, yes, but privatisation of ISRO, no,” he says.
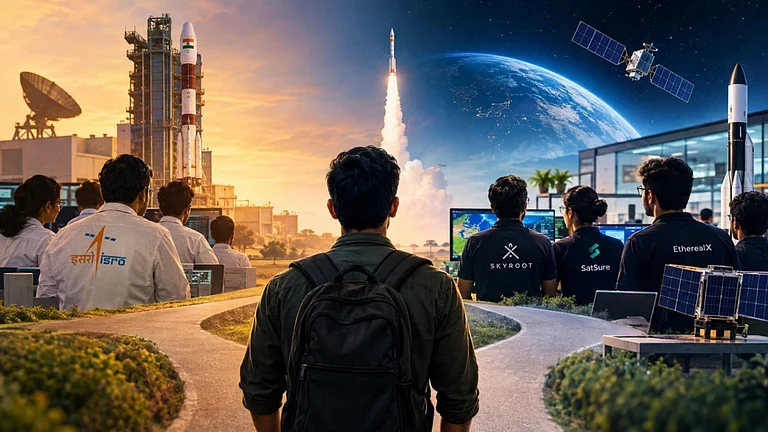
The bigger hurdle, however, may not be technology. The private sector is already developing technologies of its own, including hyperspectral capabilities, while companies such as Skyroot and Agnikul are developing rockets that differ significantly from those built by ISRO. The immediate constraint, the association argues, is "capital".
Advertisement
This makes financing one of the central challenges for India’s space ambitions. The association has called for a wider range of support like PLI schemes, while existing mechanisms such as the Technology Transfer Development Fund and the ₹1,000-crore start-up fund are expected to help companies move up the funding curve.
At the same time, the government is expected to remain an anchor customer, particularly as private companies seek the scale needed to compete globally. The association also argues that opening the sector need not mean draining ISRO of talent. “It is about creating more talent in the private sector, not about losing the talent that already exists,” he adds.
Advertisement
Edited Excerpts:
ISRO says this is not privatisation but the creation of an “ISRO-led national space ecosystem”. Where, in practical terms, should the line be drawn between what ISRO must continue to own and execute and what should be handed over to private industry?
In June 2020, the government decided that privatisation of space will take place. Thereafter, they took out a space policy draft, shared it with industry, with all stakeholders. Then a policy came out, which defined the roles for each and every one. And that policy defines what ISRO should do, what NSIR should do, what IN-SPACe should do. And very importantly, what the non-government entities should do.
Non-government entities meant the private sector and the public sector. Coming to non-government entities, it is already defined for them that they can be in all domains like communication, remote sensing, and others. According to the policy, asteroid mining or colonisation of space is even permitted by private agencies.
It allowed them to undertakr every kind of activity in space. It was a very forward-looking policy, in alignment with the new space age. Today, there is no clear line saying, "This is what ISRO will do and this is what the private sector will not do.”
Of course, security remains a critical issue, and that will continue to rest with the government. ISRO remains the primary agency for all matters related to space in India. Research and development, interplanetary missions such as Gaganyaan, Antariksh mission and missions to the Moon would all be undertaken by IRSO. So, there is a clear definition of roles in this regard.
So, ISRO continues to do what it has traditionally done, while routine commercialisation activities, which had made its spectrum of responsibilities too large, are taken up by the private sector. The private sector is even involved in allocating spectrum and deciding which satellites belong to private companies and which companies they will procure them from.
These are routine activities, rather than research and development, and this is where IN-SPACe was brought in to oversee the private sector’s activities.
Will it increase competition between ISRO and private players?
We can't call it competition. Who can compete with the government organisation? It is co-travelling and cooperation. And to put it in the words of the previous ISRO chairman, space in India was led by ISRO for the last 60 years, but now the space enterprise will lead it.
And what defines a space enterprise is an ISRO-led ecosystem in which the private sector, academia and start-ups are all part of it.

DRDO has increasingly moved towards technology transfer and industry partnerships. Should ISRO adopt a similarly aggressive model of transferring technologies and capabilities to private industry?
Firstly, let me tell you that, as research and development organisations, between ISRO and DRDO, ISRO takes the lead. And one thing ISRO has done is create an ecosystem in India.
While ISRO has been the lead integrator in making launch vehicles or satellites, it has involved the private sector for a long time, whether for assemblies, components or various other parts. So, we have a well-evolved ecosystem that provides components and assemblies to ISRO.
What is now being planned, and the first step was taken about two and a half years ago, is for the LVM3 to be manufactured by the private sector. The first contract for five PSLVs was given to a combination of HAL and L&T. Even in the case of the PSLV, a large part of the work across its different stages is already done by the private sector, much before privatisation took place.
So, there is a system in which capabilities have already been developed in the private sector. Now, there is an opportunity to allow the private sector to take on more activities that are less R&D-intensive. The core R&D and interplanetary missions, which are critical for India’s space programme, will continue to remain with ISRO.
And if we talk about what should remain exclusively under government control. So, it should be the launch vehicles. As you are aware, even under foreign direct investment rules for launch vehicles, we have kept the limit at 50% and have not allowed it to go beyond that. The primary aim is to ensure that control stays within India.
Even now, when technologies related to the PSLV and LVM3 are transferred to the private sector, it will be done with significant support from ISRO. There is nothing to suggest that ISRO will no longer be able to build rockets. If ISRO needs to build a rocket for its own work or launch something, it will continue to do so. ISRO retains the primary intellectual property; it is transferring technology, not the IP.
A new-generation launch vehicle will also be required if we are to send a human to the Moon. This will be developed with ISRO as the lead, with cooperation from the private sector. So, this is privatisation of space, not theprivatisation of ISRO.
Do you think there is any risk of pushing private participation too aggressively?
Privatisation has started since the space policy was announced. Since then, two companies have conducted sub-orbital launches, while Agnikul has conducted an orbital launch. Around five companies have also developed satellites, and many other activities are underway. So, privatisation is progressing, and I am not sure what the risk would be.
Even 52 satellites being developed for the defence forces under the Satellite-Based Surveillance-3 programme reflect the government’s confidence in the private sector. Out of these 52 satellites, 31 are being developed by three private companies, while 21 are being developed by ISRO. This is being done under NSIL, or NewSpace India Limited.
So, privatisation of space in India brings in more value and creates more opportunities.
The current government has also been using space as a platform for cooperation with multiple countries. Wherever the Prime Minister travels, space cooperation with various countries is part of the engagement. But this cooperation is not limited to ISRO. It is government-to-government cooperation, involving both ISRO and the private sector.
How do you prevent a situation where the capability exists in the private sector but the national institution itself no longer retains enough hands-on expertise?
This will never happen because ISRO has to remain the anchor. There are no plans to remove ISRO’s capabilities or reduce its facilities in any way. Even the existing spaceport will continue to remain with ISRO.
An additional spaceport is being developed, which will also be built by ISRO. However, for its day-to-day operations and routine activities, some of the work may be outsourced to the private sector.
It is similar to what has happened with airports. If airports have been given to the private sector, the government has not lost its primary domain over them. Can the Mumbai or Delhi airport be denied to government agencies? No. But routine activities that were earlier handled by the Airports Authority of India are now being carried out more efficiently by the private sector.
So, India wants to build a much larger and more diversified space economy.
India wants a much larger space economy. But what is the business model that will make private investment in space commercially viable at scale? Where will the returns come from?
The first and largest support for the space industry to come up has to come from the government as the anchor customer. And it goes beyond the defence forces. Ministries will use, or will increasingly use, different kinds of space products in the future.
The Ministry of Environment, for instance, uses space technology extensively for weather predictions. The Ministry of Agriculture can use it to improve agriculture in India, while the Ministry of Education can use it to provide education in distant areas. Space technology is also critical for disaster management because, when everything else fails, SATCOM can provide connectivity.
The concept worldwide is that governments are the anchor customers for the space industry. But beyond that, for Indian companies to be financially and commercially viable, they will have to become global. They will have to develop capabilities that allow them to compete in global markets.
The initial signs of this are already there. Hyperspectral-domain satellites, for instance, are very rare in the world, and one Indian company is developing a hyperspectral constellation. Similarly, OptoSAR, which combines optical and SAR sensors in a single satellite, has not been done anywhere in the world. It is now being attempted by an India company.
Is the bigger constraint today actually technology, or is it capital? If India wants to compete with the US, China and other major space economies, how much private capital will have to come into the sector?
Initial financial support will have to come from the government, whether through grants, incentives, SEZs or other initiatives. And the steps in that direction are already taking place.
States across India have also announced space policies and are trying to attract start-ups and space companies to set up operations in their states because they see opportunities for jobs, development and growth.
But the model, ultimately, would be: the government as the anchor customer, followed by companies reaching global partners.
Fortunately, venture capital has started flowing into many Indian start-ups over the last four to five years, and we have been getting funding through VC ecosystem. But a larger amount of money will have to come through government support.
Recently, a significant amount from the RDIF fund was given to four or five start-ups. There is still much more to be done because substantial financing is required for R&D, but steps in the right direction are being taken through various government schemes.
There is also the Technology Transfer Development Fund (TTDF), which was started by ISRO. Another fund of ₹1,000 crore was also released to support new start-ups, with amounts ranging from ₹50 crore to ₹150 crore being given to various new age ventures.
A lot more needs to be done in terms of financing because space technology requires significant R&D investment.

What other schemes, funds or initiatives should the government introduce to encourage greater private-sector participation in the space sector?
Our ask on financial incentives has evolved from PLI to lower taxes, tax holidays and lower GST, and now to new models of funding by financial institutions. In space, there are no assets as such, and there is no annuity that comes immediately.
So, for any loans to be given to the private sector, new models have to be created. And that is what we have been appealing for.
If more manufacturing and routine operations move to industry, what happens to ISRO's engineers and scientists? Could India actually end up losing talent to the private sector, or could this create a much larger talent pool for the entire space ecosystem?
Not at all. It is about creating more talent in the private sector, not about losing the talent that already exists. That is the wrong way of looking at it. What is happening, and will happen, is that more talent will be created in the private sector to carry out space activities, alongside the talent that already exists in ISRO.
Yes, retired ISRO scientists and others do advise startups and help with hand-holding because their valuable experience needs to be utilised by the nation. But to say that ISRO’s resources, scientists or capabilities will move to the private sector is incorrect. That is not happening, and it will not happen.
If India becomes dependent on private companies for critical launches or space infrastructure, what happens if a company fails financially?
Even for critical capabilities, and the most critical in space, as you said, is launch vehicles, the responsibility would be taken up by companies with very strong credentials. In the future, as launch becomes part of critical infrastructure, it would not be some company that is simply looking to make quick money and move on. There will be well-recognised companies with the capabilities and heritage to do this.
That said, this capability will not be developed by just one company; it will be spread across multiple players. Even in small launch vehicles, there are already two companies, Skyroot and Agnikul, and more companies are coming in the future. So it is not a situation where one company fails or faces financial difficulties and everything is lost. That cannot happen.
The same applies to satellite manufacturing, which will be undertaken by multiple companies. And, of course, space applications will involve hundreds of companies.
What is the one capability that India cannot afford to leave entirely to the private sector?
The most critical capability in space is launch vehicles. That is why, as I said, FDI in this area has been structured to ensure that control of these companies remains in India. While there is 100% FDI allowed in certain parts of satellites, in launch vehicles, the limit has been kept much lower.
What could be the biggest challenge for India’s space economy? Will it be technology, especially for the private sector, or will it be capital?
Presently, I would say capital.
Because technology is also related to capital. In a way, it requires R&D, and if capital comes in, the private sector will also invest in research and development and develop products that are better and better.
And let me also put one thing into perspective. The private sector is not creating things only through technology that has been transferred to it. They are developing their own technology as well. Hyperspectral technology, for instance, is a technology that has been developed by the private sector.
The rockets being developed by Skyroot and Agnikul are also very different from the rockets produced by ISRO. So there is R&D and development already being carried out by the private sector, and this will continue.