

India’s start-up ecosystem has come a long way from the early days of the IT boom. Today, a new generation of founders is building businesses across sectors, backed by a growing pool of private capital and a more proactive government. In their book ‘Lift Off Nation’, Peak XV Partners’ Rajan Anandan and veteran entrepreneur Saurabh Srivastava examine what has brought the ecosystem to this point and what it will take to sustain its momentum.
In a conversation with Outlook Business, they discuss India's deep-tech ambitions, the need for technological sovereignty, the opportunities in AI and the structural changes required to turn its start-up potential into lasting economic growth.
Who is Lift Off Nation written for, and which readers should take the most from it?

1 November 2026
Get the latest issue of Outlook Business
Saurabh Srivastava: Policymakers should read every chapter. The book should also be read by start-ups, which can draw energy and encouragement from the examples, and by investors, who can see that investing in deep tech can generate good returns.
Rajan Anandan: Existing founders and aspiring entrepreneurs should read it because it gives them a sense of what is happening and of the opportunities available in India. There is innovation in many segments, more capital, proactive government support and an active IPO market. I sent the book to some of my former colleagues at Google, and several said it had made them think about starting companies themselves.
Advertisement
What did the research reveal about how quickly the start-up ecosystem is changing, and what did you have to rethink while writing the book?
Rajan Anandan: We began the project in January 2023, expecting it to take about six months. It eventually took three-and-a-half years and involved more than 180 interviews with founders, investors, academics and others. The pace of change during that period was striking.
Artificial intelligence was not part of our original outline. Our software chapter was initially much more focused on SaaS. As AI developed, we added a separate chapter and brought in examples to reflect the transformation taking place. Deep technology was also at an earlier stage when we began. Initiatives such as the RDI fund had not yet taken shape; during the research, India began doing several of the things we had argued it needed to do.
Some of the company examples also had to be viewed in the light of changing circumstances. We found real-money gaming interesting, but the regulatory environment changed substantially. We did not have a full chapter on the sector, though we had included examples of companies operating in it. The geopolitical environment changed too, making technological sovereignty more important. The book argued that smaller AI models would become important, and it has been striking to see how quickly that conversation has moved. A book written over several years can capture only a point in a rapidly changing ecosystem.
Saurabh Srivastava: When researching, you have to be prepared to discover that some of the things you had believed were not right. You have to remain open to what you see, even when it does not support your initial view. Listening to people, the market and other people’s experiences is how you keep learning and stay ahead.
Advertisement
Why did you choose to open each chapter with a founder’s story? Could that put personalities ahead of the systems that made the companies possible?
Saurabh Srivastava: We could have written about our own views and theories, but that would have been boring. Using actual people, companies and investors brings the subject alive.
Rajan Anandan: A founder’s story is an engaging way to introduce the larger theme. In the consumer brands chapter, for example, we could have begun with a list of reasons why new brands were emerging. Instead, we tell the story of Mamaearth and its journey from an idea to an IPO in seven years. That gives readers a way into the larger forces at work. At the end of the day, this is a book, not a PhD thesis. We wanted people to keep reading it.
Many of the companies featured are successful and some are connected to your investment networks. How did you select the examples and guard against bias?
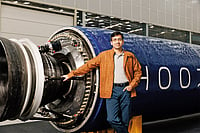
Rajan Anandan: Some companies in the book are part of the Peak XV Partners or Indian Angel Network portfolios, but many are not. PhonePe, for instance, is a major example in the fintech chapter, but it is not a Peak XV portfolio company. Neither Peak XV nor the Indian Angel Network invested in Skyroot or Agnikul. We wanted to include companies that had made a mark or illustrated a larger theme, not simply companies connected to us.
In consumer brands, for example, we wanted to show how quick commerce has made it possible for brands to scale quickly. Health Factory was one example; SuperYou, which is not a portfolio company, was another. We also wanted to include younger businesses that could offer a glimpse of what is coming, even if they were not yet unicorns or large revenue generators.
Some companies came to us through conversations with people in the ecosystem. We found StringBio and other life-sciences businesses while speaking to the team at C-CAMP. We wanted to understand the innovation emerging from incubators and research institutions, including in areas such as biotechnology and CAR T-cell therapy. Other examples came through conversations with e-commerce platforms. The book therefore includes both recognised leaders and less familiar companies working on interesting problems.
It is also important to remember that successful start-ups go through difficult periods. On average, a successful company may face five near-death moments. Ather’s Tarun Mehta told us they had faced six. These moments can involve running out of cash, a co-founder leaving or a competitor entering with much more capital. start-ups follow a power-law pattern: a small proportion of companies create most of the value. That is visible across successive waves of e-commerce, from Flipkart to Meesho and then quick commerce, where Blinkit is leading.
Saurabh Srivastava: We did not see ourselves as conflicted. We selected what we considered the best companies and made sure the examples covered different sectors rather than just one kind of business.
The NASSCOM-McKinsey report helped give India’s IT industry a shared ambition. Is Lift Off Nation intended to play a similar role for the start-up ecosystem? What would success look like by 2047?
Rajan Anandan: Yes. The book is intended both to explain why this is the moment for India’s start-up ecosystem and to serve as a rallying cry. The ecosystem is already at a very different stage from where the IT industry was when the NASSCOM-McKinsey report was written. The combined public and private valuations of funded start-ups are now more than $400 billion, while the public market capitalisation of IT services companies is about $350 billion. Those are the figures I cited in the book discussion.
We wanted to document the building blocks behind this progress: world-class founders starting companies, innovation across sectors, Indian founders building for global markets, a fivefold increase in private and venture capital, a more active IPO market and government support. There is still a great deal to do. Research and development is the biggest gap, and ease of doing business also needs attention.
If India gets these things right, innovation and entrepreneurship can play a significant role in achieving Viksit Bharat. The ambition is for India to become the most innovative nation in the world. We are already leading in areas such as fintech and consumer commerce, while sectors such as space technology and AI are still at an early stage of their opportunity.
Saurabh Srivastava: The NASSCOM-McKinsey report was the inspiration. The software industry was growing at about 100 per cent, but from a small base. When it reached roughly $1 billion, NASSCOM brought in McKinsey to assess what was possible. The resulting report said the industry could grow from $2 billion to $50 billion within a decade. It turned out to be almost exactly right and became a showcase for what a shared ambition could achieve.
We asked why a similar exercise could not be done for start-ups across sectors, rather than for software alone. The ecosystem now includes companies serving the domestic market as well as those building for export markets. There are repeat entrepreneurs, founders returning from overseas and funding from domestic and global venture capital firms, alongside government support through the $12.5-billion Research, Development and Innovation (RDI) fund.


What has changed in the profile of Indian founders? Is frugality the defining advantage of the new generation?
Rajan Anandan: I would clarify the premise. The first chapter is not principally about frugality; it is about world-class talent starting companies. In 2010, India had no unicorns. InMobi became the first in 2011, and the ecosystem has since produced many more. A growing number of founders who are now starting up have experience in global technology companies and in India’s fastest-growing start-ups. They have learnt how to decide what to build, develop a product, ship it, understand user needs and drive revenue.
Take Lalit, for example. After studying at an IIT and working at a semiconductor company, he tried to start a business. He then joined Flipkart, where he learnt how to build and scale a company, before starting his next venture. His team was not beginning from scratch when it came to product development or understanding users. That accumulated experience is the central point of the chapter. Frugality is mentioned, but it is not the defining argument.
If smaller AI models could become more affordable and the application layer offers significant opportunities, why does India also need sovereignty across the AI stack?
Rajan Anandan: It is extremely important for India to have sovereignty in all critical technologies, including AI, semiconductors, advanced manufacturing, quantum computing and defence. Given the way geopolitics is changing, the next 30 years are likely to look very different from the last 30. India therefore needs sovereignty in every part of the AI stack, not just at the application layer.
India is in a good position in applications, and there are also Indian companies building globally competitive tools. At the model layer, we believe smaller models can meet a large share of domestic needs. Models in the range of 30 billion to 100 billion parameters can serve 90 to 95 per cent of what enterprises need, as well as many consumer use cases, without requiring the billions of dollars needed to build the largest frontier systems.
That does not mean the frontier can be ignored. Larger models will be needed for more demanding work, including advanced coding, cybersecurity and scientific discovery such as finding new molecules, drugs and materials. Those efforts require enormous capital, and the scale of global investment is far ahead of what India currently puts into venture capital.
The other constraints are compute and semiconductors. India was behind on compute, but investments announced by large Indian groups and cloud providers are beginning to address that gap. Advanced semiconductor manufacturing will take longer and remains one of the hardest parts of the stack to build. Our argument is that India should take a ten-year view. Digital payments and space technology show how the country can move from a late start to global leadership over time. We believe the same opportunity exists in AI, provided India invests in capital, research talent and capabilities across the stack.
Series B and later-stage funding remain difficult for deep-tech start-ups. What could help close this capital gap?
Saurabh Srivastava: The government has created the Research, Development and Innovation Fund, with a corpus of $12.5 billion. It is meant to be invested in deep-tech companies across different sectors that can contribute to strategic autonomy and technological sovereignty. That has changed the whole equation for companies that need patient capital.
Rajan Anandan: The RDI framework is also expected to anchor 50 per cent of the corpus of selected venture capital funds investing in deep tech. The earlier SIDBI Fund of Funds programme provided 30 per cent, which was itself progressive. A 50 per cent anchor is an unusually strong signal of the government’s intent. It should help create new deep-tech funds, which can raise further capital as they establish a track record.
There is also growing interest from global sovereign investors, corporates and Indian companies. GIC and Temasek, Singapore’s sovereign wealth funds, have invested in Skyroot. Reliance led the Series B round of Digantara. Deep tech remains the final frontier for India’s start-up ecosystem, but these are encouraging early signs.
The book recommends reserving at least half of government tenders for Indian products, even when there is only one domestic bidder. Where should the line be drawn between enabling local companies and picking winners?
Saurabh Srivastava: Indian products have historically been looked down upon. One way to change that is for the government to start buying high-quality, world-class Indian products. When the government begins purchasing them, it gives other buyers the confidence to do the same. That was the idea behind the recommendation.
Rajan Anandan: We are not suggesting that the government compromise on quality. If quality is comparable, there should be a preference for Indian technology because the country needs to build technological sovereignty. Some Indian defence companies are world-class but much smaller than their global peers. They can find it difficult to win large contracts against companies with greater scale.
In critical sectors such as semiconductors, space, defence and AI foundation models, the government should play a catalytic role, including as a first buyer. The point is to help capable Indian companies build scale in areas that are strategically important, not to lower the bar on quality.
AI could disrupt IT services and entry-level jobs. How serious is the employment risk, and where could new opportunities emerge?
Rajan Anandan: AI is at the beginning of an industrial revolution. During the original Industrial Revolution, nobody could have predicted all the jobs that would eventually be created. The proportion of people working in agriculture fell over time, but the transition took a long time. AI will undoubtedly automate some existing roles, but it will also create new ones that are difficult to predict today.
One example in technology is the forward-deployed engineer, a role that combines technical ability with working closely with customers. Microsoft has said it plans to hire 6,000 people for such roles. There will be new opportunities in other industries too. India should use AI to create new roles and build capabilities in areas such as healthcare delivery, where technology can help expand access and services.
IT services companies will also have an important role. AI models are already more capable than the extent to which they have been implemented in many enterprises. Banks, hospitals, retailers, energy companies and other institutions need help transforming their operations with AI. IT services companies are well placed to provide that support, although they will need to build new capabilities and may not hire as many people as before. They can remain large employers while evolving into AI-transformation companies.
What should the failure rate look like in a healthy start-up ecosystem?
Saurabh Srivastava: There have probably been more than a dozen failures among the roughly 10,000 funded start-ups being discussed. The proportion should be closer to 50 per cent. If the failure rate is not that high, it may mean start-ups are not being ambitious enough and are playing too safe.
If we meet again in 2030, what would make you feel that the book’s thesis was right?
Saurabh Srivastava: Based on my experience with what happened after the NASSCOM report, my expectation is that we will be sitting here saying we were not ambitious enough in our projections. That is the thought that comes to mind.