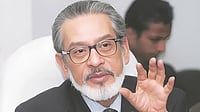


CineNow founder Rohit Dalmia is betting on institutional capital to bring structure to India’s film-financing ecosystem.
With ₹1,350 crore raised, CineNow plans to fund 30 films over six years.
Dalmia says the his model will give producers longer-term “scale capital” to build a bank of IP.
For decades, Indian cinema has relied on fragmented financing, from producers and studios to private financiers and pre-sales. Rohit Dalmia, founder and chairman of UAE-based CineNow, believes institutional capital can change that. With ₹1,350 crore raised to finance films and entertainment IP, Dalmia is building a structured, fund-led model for Indian cinema. His plan is initial plan is to fund 30 films over the next six years without retaining the film IP after its release.
“The producers who are passionate about the industry, who want longer-term financing, almost a rolling credit line, and who are sitting on good scripts but are tired of paying interest or sharing the IP they have created—that is who we want to work with. For them, it becomes scale capital. They can use us to create a solid bank of good IP over the next six years. Once they have achieved that, they can go for a PE deal, M&A or whatever comes next,” Dalmia says.

1 September 2026
Get the latest issue of Outlook Business
Dalmia, who has no prior connection to the industry, has built a 30-member team, including producer and media entrepreneur Siddharth Roy Kapur as principal adviser to the founding team.
Advertisement
In an exclusive interview with Outlook Business, CineNow founder Rohit Dalmia explains how he wants to change film financing in India.
Can you explain how CineNow is different from the current film financing ecosystem in India?
CineNow is an ecosystem where there is a marriage between capital and technology, with IP being the product or asset base. Film financing has traditionally been a messy scenario.
You can’t just bring capital and expect people to change. You have to give them a platform that is structured and governed. If it is business-friendly, producers will get on board. We aren’t going to individual producers saying, “Give us a script, we will fund it.” We don’t have existing relationships, past baggage or obligations. We have created a structure with capital and a level of governance that this industry has not experienced before.
It is also a filter. The producers who are passionate about the industry, who want longer-term financing, almost a rolling credit line, and who are sitting on good scripts but are tired of paying interest or sharing the IP they have created—that is who we want to work with.
For them, it becomes scale capital. We are not here to provide seed capital in a typical VC scenario. We are here to provide scale capital. Think of it as Series A.
They can use us to create a solid bank of good IP over the next six years. Once they have achieved that, they can go for a PE deal, M&A or whatever comes next.
How does an organisation become big? It has pedigree. It has already raised funds and produced movies. Now it can piggyback on us and scale to a certain level. That attracts larger players, such as American studios, for example. That is when they can have a PE deal.
So, we are an ecosystem or platform that gives them that opportunity. But it is designed for committed producers, good scripts and people who want to be disciplined.
Advertisement
Help me understand how this mechanism works.
The deal terms are very simple and publicly available. The first thing is that we can fund up to 100% from script to release. Technically, the producer has no equity in the financing.
That does not mean we only finance a project as a presenter after it has already been produced. A lot of filmmakers need last-mile funding—they have funded 70% and are short of the remaining 30%. Or they may simply need money for marketing expenses.
We participate at every stage of the filmmaking process. First, the IP always belongs to the producer, but it is exclusively mortgaged to us. So, I now have collateral.
When the film is released and monetised, we work on a 60:40 ratio. Sixty per cent of the profit is ours and 40% belongs to the producer. The producer has no skin in the game, so he cannot get more than I can. A 50:50 arrangement would not be fair. So, it is 60:40.
If the film makes a profit, he pays me back my principal along with my profit share, and I release the deal back to him. He remains the owner of the IP.
If the film loses money, I take the recovery risk. Let’s say it is a ₹100 crore movie and it makes only ₹70 crore. That ₹70 crore comes to me, but the IP is also with me. I then tell the producer: if you want this IP, cover my ₹30 crore loss and keep it.

Can they do that by working with you again?
He can work with me constantly. Even the ₹70 crore that came back has to be redeployed because I have a six-year life cycle. It is not simply a profit-and-loss game; it is a trading game.
That ₹70 crore came in, and I need to deploy it into the next film, whether with the same producer or someone else. Our focus is that, because we have such an expanded and professional team, we are finally putting money where our mouth is. We are saying: if we greenlight it, I am ready to take the hit.
Otherwise, what is the difference between me and anybody else? I am happy to take the hit and be part of the process. But in return, I have my 10 commandments. You are going to follow them, and I finally have complete visibility and transparency, which I wouldn’t necessarily get if I were simply a partner.
Indirectly, every producer is becoming a line producer. But we don’t take those credits. Our credit is “finance partner”. We are not a producer and we are not a studio. A lot of people call us a “posse studio”. I can understand why, because from the outside, the structure can look similar.
Is the Indian market mature enough to absorb those IPs?
It is. I’m not saying I will get a good value for them, but at least I will get something for them. You could say that if you make bad films, there is a good chance I am going to lose money.
But I say we lose money on all 30 films, and it doesn’t affect my fund. Think from a fund mentality. I have two allocations. One is presentation financing. That is all about quick, secured returns. That is the larger chunk we want to participate in—say 60%.
The balance is 40%, and I am happy to deploy that into films.
Let’s say out of ₹1,000 crore, ₹400 crore goes into films and I get only ₹200 crore back. I have made a ₹200 crore loss on the film side. That can happen.
But because I have been recycling the money for six years, even if I get a 10% return on bridge financing and can do that twice a year, that is a 20% return.
So, the ₹200 crore loss can still be recovered through the bridge-financing business. I am not putting ₹1,300 crore into making 30 films and hoping one of them becomes a blockbuster. If I get one 'Dhurandhar' out of it, then 30 films could become 50 films. That is the trading and compounding effect of finance.
How are you mitigating risks in such an unorganised ecosystem?
In startups, you burn the money and literally get something or get zero. In films, you are not necessarily getting zero back. Someone is going to watch it in a theatre. An OTT platform may buy it at some price.
So, I am not in a position to lose my full money. Even if I lose a little money on every film, that cumulative value can be recovered from the other arm, which is bridge financing, because that generates high returns and I can potentially do two or three cycles a year.
We are not fools with a lot of money trying to burn it in the film market. We have studied the market very deeply, identified the risk factors and plugged them in.
We are not eliminating risk. Nobody can eliminate risk. What we are doing is, first, trying to mitigate it, and second, trying to distribute it so that one person, party, producer, fund or investor does not take a one-or-zero position.
Is it only films, or will you also finance web series and television shows?
Only films. Only commercial films, and theatre first. We are diversifying by genre and language. Studios do that as well, so that is not unique. Then we are diversifying through a slate approach. We are not here to do one thing. We want producers to use our capital to create a good IP portfolio that we are willing to finance.
That also means we are not dependent on one producer; we are working with multiple producers.
At the performance level, we are not only dependent on the performance of a film because we also have a parallel financing activity, which is much more secure. I am happy to cover the losses. And if everything goes wrong, at least I am sitting on some residual value—the IP.
I am making 52 films a year so that I can release one film every week, so that I can hold the whole release window for the year.
You are not from the entertainment business. You have onboarded Mr Siddharth Roy Kapur. Has he helped you understand the industry and figure out whom to approach?
In one way, he did help. He contributed significantly to helping us put the team together, and I would definitely give him credit for that.
But try to understand: everything with us is objective and merit-based. Anything beyond the producer is not my problem. Not being from the industry means there are no relationships. I have no obligations and no baggage. I can make decisions that are best for my investors.
When it comes to market access, we now have 30 people on board. It is their job to bring that access to the market.
We have an investment committee comprising seven members. Two are me and my CFO, because that is a statutory requirement. Three are from the industry and two are investor-facing. We have a combination of creative and distribution expertise, as well as a purely financing and ROI perspective. Together, we decide which films get made.
Each individual votes based on his own expertise. I vote with one thing in mind: can this generate an ROI that is beneficial to my investors?
What key safeguards have you put in place for the fund?
We are bringing completion bonds for all the films we finance. It’s a very common principle in the West; it happens everywhere, but not in India. Part of the completion bond is also to monitor the quality of the output and make sure the film is completed as per the script that was locked in.
We don’t intervene, but we have put a governance structure in place to make sure that happens. If it is not done correctly, the insurance companies will pay us.
The milestones are defined by us. We don’t fund in India; we fund locally in the UAE. These are the safeguards we have put in place.