

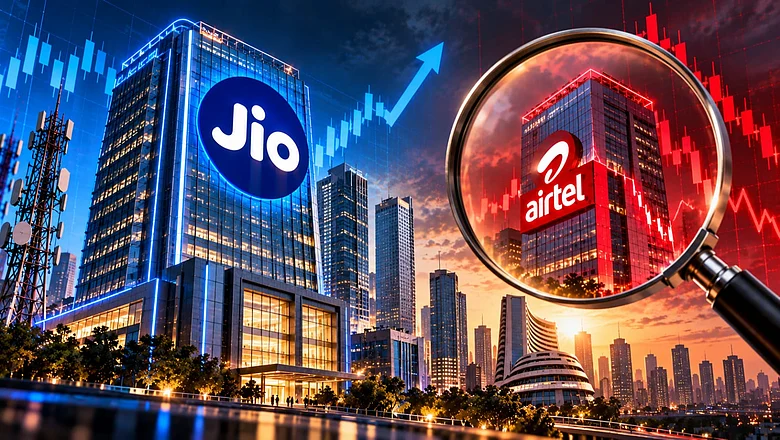

Despite Jio’s larger subscriber base, Motilal Oswal sees Airtel as broadly comparable on valuation, helped by stronger cash generation and returns
Airtel’s wireless EBITDA grew faster between FY20 and FY26, but Jio is expected to grow EBITDA faster over FY26–29
A Jio listing could also strengthen the case for telecom tariff hikes, potentially benefiting both Airtel and Jio
The proposed initial public offering (IPO) of Jio Platforms could do more than unlock value for Reliance Industries. According to Motilal Oswal Financial Services, a Jio listing could establish a valuation benchmark for the telecom sector and potentially create room for a re-rating in Bharti Airtel.
Jio Platforms is seeking an equity valuation of around ₹11 lakh crore ($114 billion) in its proposed IPO, as per Bloomberg (BBG). The figure is broadly in line with the brokerage's ₹11.2 lakh crore valuation for Jio Platforms and translates into roughly 12x FY28E EV/EBITDA, meaning its enterprise value is equivalent to about 12 times its estimated EBITDA for FY28.

1 October 2026
Get the latest issue of Outlook Business
At a potential ₹11 lakh crore valuation, the brokerage said that Jio Platforms would be valued at about 17% above the implied 10.3x FY28E EV/EBITDA multiple of Bharti Airtel’s India business at its current market price.


However, it does not see a case for a meaningful valuation discount for Airtel relative to Jio. While Jio has the larger wireless and home broadband subscriber base along with the greater influence over industry pricing, Motilal Oswal said Airtel’s stronger free cash flow generation and return on capital employed support a broadly similar valuation multiple.
Advertisement
For comparison, the brokerage valued Jio Platforms and Bharti Airtel’s India business at around 12x FY28E EV/EBITDA in its estimates. Bharti also has exposure beyond its core India wireless business, including stakes in Indus Towers and Airtel Africa worth about ₹1.25 lakh crore, based on a 25% holding-company discount, along with businesses such as data centres and financial services, it said.
Jio IPO Could Make RIL’s Discount More Visible
The listing could also make Jio’s contribution to RIL’s valuation easier for investors to assess.
According to Motilal Oswal's estimates, RIL owns about 66.4% of Jio Platforms. At its ₹11.2 lakh crore valuation, RIL's is worth about ₹7.44 lakh crore, or ₹550 per RIL share, before applying a holding-company discount. The brokerage applies a 25% discount, bringing the value attributed to Jio in its RIL target price to ₹413 per share.
Advertisement
The brokerage estimates that RIL’s current share price already implies an 18-36% discount on its Jio stake, depending on the valuation assigned to Reliance Retail Ventures.
This suggests that a Jio listing may not necessarily create an entirely new discount for RIL, but could instead provide greater visibility into the value of its digital business.
Motilal Oswal has retained a ₹1,530 target price for RIL.
Jio vs Airtel On Key Metrics
On the current operating picture, Jio has the larger subscriber base, while Bharti Airtel generates higher revenue per customer and has stronger profitability metrics.
According to Motilal Oswal, Jio's wireless subscriber base for FY26 stands at 497 million, compared with 373 million paying subscribers for Bharti Airtel. Jio's subscriber base is projected to rise to 562 million by FY29, while Airtel's paying subscribers are expected to reach 402 million.
The difference is reversed when it comes to average revenue per user (ARPU). Airtel's wireless ARPU increased from ₹136 in FY20 to ₹254 in FY26, compared with Jio's increase from ₹130 to ₹203. Airtel therefore continues to generate more revenue per subscriber despite having a smaller customer base. The brokerage expects this gap to remain, with Jio's ARPU rising to ₹244 by FY29 and Airtel's to ₹322.
Jio has nevertheless built a larger wireless revenue pool. Its wireless revenue rose from ₹543 billion in FY20 to ₹1,180 billion in FY26, while Airtel's increased from ₹461 billion to ₹1,121 billion.
The profitability gap becomes more visible when margins are compared. Airtel's wireless EBITDA rose from ₹170 billion in FY20 to ₹680 billion in FY26, while Jio's increased from ₹216 billion to ₹698 billion. Over the same period, Airtel's wireless EBITDA grew at a 26.1% CAGR, compared with 21.6% for Jio, according to MOFSL.
Airtel has also seen a sharper improvement in margins. Its wireless EBITDA margin increased from 36.9% in FY20 to 60.2% in FY26, while Jio's rose from 39.7% to 54.2%.
Motilal Oswal expects both companies to expand margins over the next few years, but Airtel is expected to retain the advantage: its wireless EBITDA margin is projected to rise to 64.7% by FY29, compared with 57.1% for Jio.
That difference is important for the valuation debate. Despite Jio's larger scale, MOFSL does not believe Airtel deserves a significant discount to Jio because of its stronger free cash flow and better returns on the capital it employs.
Tariff Hike Could Be A Trigger For Jio, Airtel
Beyond valuation, Motilal Oswal expects the Jio IPO and Vodafone Idea’s proposed fundraise to strengthen the case for another telecom tariff increase.
The brokerage has built a roughly 15% smartphone tariff hike in December 2026 into its estimates, alongside other operating assumptions, and projects Bharti Airtel's EBITDA to grow at a 14.6% CAGR over FY26–29E.
"After the JPL IPO and Vi’s impending fundraise, we believe the case for a tariff hike is stronger and build in a smartphone tariff hike of ~15% in Dec’26, which should provide visibility on delivering ~15% EBITDA CAGR over FY26-29E," the brokerage said in its report.
Its estimates show Jio Platforms growing EBITDA from ₹69,800 crore in FY26 to ₹95,700 crore in FY28, while EBITDA margins are expected to expand from 54.2% to 56.6%. Jio Platforms is estimated to post a slightly higher EBITDA CAGR of 15.2% over FY26–29E, compared with 14.6% for Bharti Airtel.
Vodafone Idea's financial position remains considerably weaker than Bharti Airtel's, according to Motilal Oswal. The brokerage expects Vodafone Idea's debt to remain high relative to its earnings, with net debt at 9.6 times FY28E EBITDA, compared with just 0.3 times for Bharti Airtel.
It also estimates Vodafone Idea's enterprise value at 15.9 times to its expected FY28 EBITDA, compared with 7.3 times for Bharti Airtel.
For investors, the brokerage’s argument is therefore less about choosing between two identical telecom businesses and more about whether Jio’s IPO can establish a sector valuation benchmark.
If Jio lists around the proposed valuation and tariffs rise thereafter, market analyst believes both Jio and Airtel could benefit from stronger earnings visibility and potential multiple re-rating.