

Record SIP flows are cushioning small-cap corrections and supporting a higher valuation floor.
Small-cap index correction reached 25%, versus 40–50% in earlier downcycles.
Elevated valuations still leave individual small-cap stocks vulnerable to sharp corrections.
India's small-cap market may be going through a structural shift, with a growing pool of domestic money changing the way the segment behaves during market corrections. Unlike previous downcycles, when small-cap indices could fall 40–50% and individual stocks could lose 70–80%, the latest correction was significantly shallower despite valuations remaining elevated.
At the centre of this change is the steady rise in domestic equity flows, particularly through systematic investment plans (SIPs). Mutual fund SIP contributions rose to a record ₹32,297 crore in August, up marginally from ₹31,961 crore in July and 14% higher than ₹28,265 crore in August 2025.

1 September 2026
Get the latest issue of Outlook Business
The number of contributing SIP accounts stood at 10.01 crore in August, while SIP assets reached ₹18.62 lakh crore, according to industry data. The broader mutual fund industry also continued to expand, with assets under management rising 1.5% month-on-month to ₹87.08 lakh crore.


The significance of these flows extends beyond the headline SIP number. With equity mutual funds recording ₹29,329 crore of net inflows in August - their 66th consecutive month of inflows - domestic investors are increasingly providing a recurring source of demand even when foreign investors retreat from Indian equities.
Advertisement
SIP Boom Is Changing The Smallcap Downcycle
The difference between the latest small-cap correction and earlier cycles is particularly striking.
According to N. ArunaGiri, Founder & CEO of TrustLine Holdings, earlier small-cap downcycles typically lasted around 1.5–2 years and saw index-level corrections of 40–50%. At the stock level, declines of 70–80% were not uncommon.
The latest downcycle, which began around late 2024 and continued until March 2026, lasted nearly 18 months broadly comparable in duration with previous cycles. But the depth of the correction was markedly different.
The small-cap index declined by around 25%, while stock-specific corrections were broadly limited to 30–40%, according to ArunaGiri. That means the magnitude of the latest correction was roughly half the levels seen in earlier cycles.
Advertisement
“In our view, the primary reason for this is the sustained and persistent domestic flows. It is difficult to find another factor that adequately explains this significant change in the behaviour of small-caps during the downcycle,” ArunaGiri said.
The shift is not limited to the depth of corrections. ArunaGiri also pointed to a change in the valuation floor of the small-cap segment.
In earlier cycles, aggregate small-cap valuations could fall from peaks of around 25–28 times earnings to the low teens during a downturn. In the latest cycle, however, valuations had reached around 30–35 times earnings at the peak but corrected only to around 25–26 times.
That suggests domestic liquidity is doing more than cushioning short-term selling pressure. It may also be helping establish a higher valuation floor for the segment.
Domestic Money Is Filling The Gap
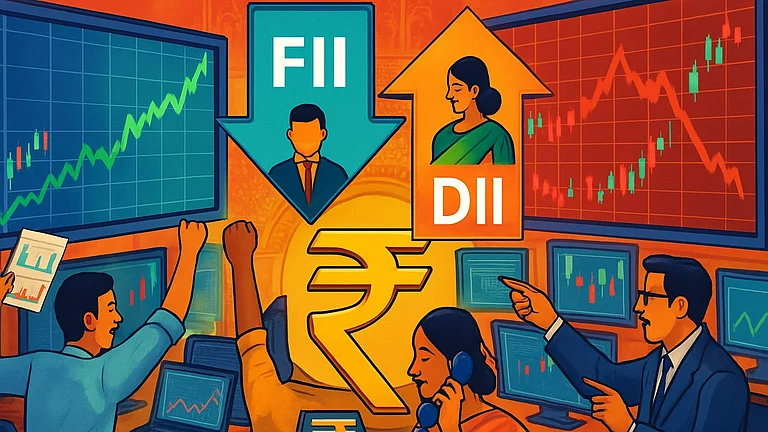
The changing behaviour of small-caps is taking place against a backdrop of significant foreign selling.
September has been particularly difficult for foreign investors, with FIIs turning net sellers in 15 of the first 20 trading sessions. Selling accelerated towards the end of the month, reaching ₹3,694 crore on September 25, ₹5,353 crore on September 28 and almost ₹10,000 crore on September 29.
The pressure has come amid crude oil prices moving above $100 a barrel, the rupee hovering around ₹96 to the dollar, elevated US Treasury yields and heightened geopolitical uncertainty.
For global investors, higher US yields make dollar assets relatively more attractive, while higher oil prices raise concerns around India's import bill, inflation and the rupee. A weaker currency can also reduce dollar-denominated returns, increasing pressure on emerging-market allocations.
Yet the domestic investor base has become significantly larger than it was during previous FII-driven market cycles.

Mutual funds, insurance companies and household savings have created a recurring pool of domestic capital, with SIPs providing a relatively steady channel of equity investment. That has helped cushion the impact of foreign selling, particularly in segments where domestic investors have a greater influence.
The contrast is visible in the flow data. While foreign investors have been selling Indian equities, domestic institutional investors have continued to deploy capital, with equity mutual funds alone recording their 66th consecutive month of net inflows in August.
This does not mean domestic investors can completely offset foreign selling. When FII selling is concentrated in index-heavy large-caps, buying elsewhere may not prevent benchmark indices from falling.
But the destination of the money matters. Domestic flows can continue supporting mid- and small-cap stocks even as foreign investors reduce exposure to large-caps.
Why Small-caps Are Holding Up
The stronger resilience of small-caps is therefore partly a function of the investor base supporting them.
ArunaGiri estimates that annual mutual fund flows have risen from around ₹1–1.5 trillion in earlier periods to ₹4–5 trillion, while SIP flows have reached around ₹250 billion a month. The latest August data puts monthly SIP contributions even higher, at ₹32,297 crore.
“If these domestic flows remain persistent, they could continue to provide a structural liquidity anchor for small-caps and support a higher aggregate valuation floor,” ArunaGiri said.
That does not mean the entire small-cap universe will benefit equally. As valuations remain elevated, individual company fundamentals, earnings and growth prospects can create significant divergence between winners and losers.
Ravi Singh, Chief Research Officer at Master Capital Services, also cautioned that higher valuations can increase the risk of sharper declines if earnings fail to meet expectations.
“Rising SIPs and strong domestic inflows are providing support to small-cap stocks by cushioning corrections and improving liquidity,” Singh said. However, he added that the trend remains dependent on continued SIP participation, household savings and investor confidence.
This distinction is important because a stronger liquidity floor does not eliminate valuation risk. It can reduce the severity of an aggregate correction while still leaving individual stocks vulnerable to large moves.
The New Small-cap Equation
The latest cycle suggests that India's small-cap market may no longer behave exactly as it did during previous downturns.
A larger domestic investor base, rising SIP contributions and sustained mutual fund inflows have created a recurring source of demand. That demand appears to have coincided with a shallower correction and a higher valuation floor during the latest small-cap downcycle.
But the same liquidity that supports valuations can also create risks if expectations move too far ahead of earnings. With small-cap valuations still materially above the levels typically seen at the bottom of earlier cycles, the market may be more resilient at the index level while remaining highly selective at the stock level.
The result is a market where domestic liquidity has become an increasingly important stabilising force, but not a substitute for earnings.
For investors, that distinction could define the next phase of the small-cap cycle. SIP flows may continue to provide the segment with a structural liquidity anchor, but whether individual companies sustain their valuations will ultimately depend on fundamentals, earnings and business prospects.