

India needs a much higher savings rate than the current 30% of GDP to sustain 8% growth, with domestic savings becoming more critical amid global uncertainty
Strong balance sheets give India Inc capacity to invest, but global headwinds hold back private capex; addressing the “missing middle” in manufacturing through labour reforms is key
Policy priorities include boosting employment quality, expanding education and skilling, and balancing high growth with sustainability goals like net zero by 2070
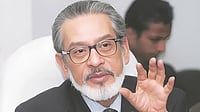
If India wants to get higher growth of 8% per annum, savings rate has to be much higher than the current rate of 30% of GDP, says S Mahendra Dev, Chairman of the Economic Advisory Council to the Prime Minister.
Buoyed by robust services activity, India's GDP growth accelerated to a five-quarter high of 7.8% in April–June 2025, surpassing expectations for the second straight quarter, the statistics ministry reported on Friday. Economists however, project India to grow at a rate of 6.3% to 6.8% in the current year.

1 September 2026
Get the latest issue of Outlook Business
According to the Economic Survey, India needs to achieve an average growth rate of around 8% at constant prices for about a decade or two to realise its economic aspirations of becoming Viksit Bharat or a developed country by 2047.
"It is known that domestic savings and net inflow of foreign capital finance gross capital formation in the country. In the context of global uncertainty, the share of foreign capital may decline," Dev adds. "Domestic savings play a critical role in augmenting capital accumulation and contributing to achieve and sustain high economic growth."
Advertisement
In this exclusive interview with Outlook Business, the Prime Minister's economic advisor talks about the government's push to consumption and growth, the role of private sector, and discussions related to taxation and finance required for India's development goals. Edited Excerpts:
Could tax cuts meaningfully boost consumption when real wages have stagnated and household debt is rising, making private-sector investment more crucial to demand?
The measures taken by the government will increase consumption in FY26 and beyond. There are many domestic tailwinds such as low inflation, rate cuts and CRR (cash reserve ratio) cut by RBI, expected good monsoon, trade diversion to India, measures in the last budget like rising capital expenditure, tax reduction, et cetera.
These tailwinds may raise both rural and urban demand by raising both investment and consumption, and some push to exports. The twin-demand approach of diversifying markets for exports and meeting domestic demand will also help small labour-intensive businesses.
Restructuring of GST rates will lead to increase in consumption and offset the external uncertainty of tariffs and geo-political situation. The Q1 of FY26 showed a GDP growth of 7.8%, beating the market expectations. Private consumption also showed a growth rate of 7% in the same period.
Regarding real wages, ILO report compares 2012 and 2022 and not recent years. There seems to be a pickup in the real wage growth of formal sector in Q1 of FY26. Similarly, RBI Bulletin of August 2025 indicates that rural demand remained resilient supported by an uptick in real wages. The rising incomes due to government measures may reduce household debt.
Advertisement
Despite tax cuts and higher public expenditure, private investment has remained weak. With global uncertainty rising, how realistic is it to expect businesses to invest more?
There is no twin balance sheet problem now. Corporate sector and banks are having more profits now and their balance sheets are in good shape. So, there is no problem of capital availability. Industry is positive about India’s growth story. Corporate sector is probably holding investing in capacity expansion due to global uncertainties and overcapacity in some countries like China. Many firms turned debt free, doubling their cash on the books. India Inc has to make new investments instead of keeping the cash.
Increasing government capex (capital expenditure) will also have impact on private sector investment. Studies have shown that creation of national highways and rural roads have increased businesses in rural and urban areas. In other words, government capex will have multiplier effects. There are some green shoots on private capex.
Many state governments are also attracting domestic and foreign private investment. Increase in rural and urban demand will facilitate more private investment. Hopefully, private capex will increase more once the domestic demand increases further and global uncertainties are reduced. Once the tariff concerns are over, there will be more opportunity for Indian industry to invest.
Factors such as ease of doing business, land and other infrastructure availability, logistics, and needed manpower attracts investment to states. The states have to make more efforts to invite FDI and domestic private investment.
There are different takes on why we are unable to raise the share of manufacturing in the GDP. Where do you stand?
The gross value added in manufacturing increased from ₹16.84 trillion in FY15 to ₹29.54 trillion in FY25, an increase of 75% in ten years. The share of manufacturing in GDP which is around 17% will rise over time. ‘Make in India’ initiative of the Indian government is to harness the potential of manufacturing. It may be noted that both manufacturing and services are needed as both are complementary.
The manufacturing sector has higher backward and forward linkages and also improves services. India has a diversified industrial sector ranging from textiles, electronics, automobiles, chemicals, pharmaceuticals et cetera. The services sector needs an expanding manufacturing sector. Thus, some of the growth in services sector is due to expanding manufacturing. One should not conclude about the contribution of manufacturing by just looking at the share of manufacturing in GDP.
On manufacturing, among other things, small size of the firms with majority operating at less than 10 workers is the major problem. And many others are between 10 to 50 workers. On the other end we have large scale manufacturing firms. Missing middle is an issue. We must have many more middle level manufacturing units with 200 to 500 workers. There is an observed tendency for firms in India to remain small. By staying small, firms lose access to institutional capital, skilled talent, and technology infusion and they are outside formal supply chains. There is a feeling that we quickly need to introduce labour reforms which can remove the missing middle problem. This can raise productivity and growth significantly.
Labour flexibility has to be done at state level. A state level analysis mentioned in the Economic Survey 2024-25 indicates that industrial progress is better in the states where business reforms were undertaken. The government is giving a lot of push to manufacturing sector. The new generation reforms announced recently focused on deregulation and easing ‘compliance burden.' There is a need for more progress on ‘ease of doing business’ at the state level.
Is it time to consider taxing wealth at the upper end to fund growth and social spending? Recent studies suggest increase in inequality and under-reporting of taxable income by the wealthy.
Wealth tax was abolished in 2015 due to several procedural difficulties such as extensive litigation, increased compliance burdens, heavy administration costs and generation of inadequate revenues. High collection and administrative costs often outweigh the potential revenue.
The consumption inequality has declined based on NSS Consumer Expenditure Surveys. National Statistical Organisation (NSO) is planning to conduct a household income survey. It may be possible to capture income at the upper end if NSS makes efforts. Even consumption for the richer classes is generally underestimated.
Despite low per capita income and limited trickle-down benefits, India has one of the world’s largest billionaire populations. Why not consider a workable wealth tax in this context?
Increasing dollar billionaires is not a bad thing. They can create wealth and increase employment. Again, imposing wealth tax is not the solution for improving revenue and increasing growth. For reducing inequalities and increasing growth and welfare, there are other instruments. Equality of opportunity has to be created. Creating quality employment, education and health provides better equality in outcomes.
Your predecessor argued for taxing rich agricultural income. Given evidence of tax evasion through agriculture, should we explore measures such as income thresholds while protecting small and marginal farmers?
According to the Situation Assessment Survey of 2018-19, the average monthly income of agricultural household is ₹10,218 in rural areas. Annual income would be ₹1.22 lakhs. A NABARD report indicates an average monthly income of ₹13,661 for agricultural households in 2021-22. Even a larger farmer income is not very high. About 86% of the total farmers are small and marginal farmers in India. Government’s tax revenue may increase only marginally by taxing agriculture. Here are also administrative costs that would outweigh revenue generated.
That said, some of the activities on agriculture land are taxed. If the land is used for non-agricultural activities or agro-processing et cetera, income is taxed. In order to widen the tax base, more non-agricultural population have to be covered.
How can India better channel household savings into funding the long-term investment needed for Viksit Bharat?
Earlier, banks had been financing more long-gestation infrastructure projects which led to more NPAs (non-performing assets). Now banks are careful in lending to long-term infrastructure projects. Historically, government used to fund infrastructure. However, it was soon realised that the involvement of the private sector becomes crucial in funding the expansion of infrastructure, improving industrial competitiveness and optimising the use of resources.
In this context, in 2021, the National Bank for Financing Infrastructure and Development (NaBFID) was created to tackle India’s infrastructure financing challenges and to catalyse the participation of private sector. NaBFID transcends the traditional role of a development finance institution which generally takes care of the problems due to market failure. This long-term funding base has attracted institutional investors, such as pension funds and insurance companies. This has demonstrated the credibility of the newly established institution. It currently covers close to 9000 projects across 34 sub-sectors, amounting the total scale to over $1.5 trillion.
It is also important to ensure that infrastructure is inclusive and sustainable. Increase in household savings in the economy, particularly financial savings is important for higher investments. Now corporates are also having cash and they should invest for financing to achieve Viksit Bharat goals.
While boosting consumption supports growth, how can India also raise savings and capital formation?
It is known that domestic savings and net inflow of foreign capital finance gross capital formation in the country. In the context of global uncertainty, the share of foreign capital may decline. Therefore, domestic savings has to increase further from the present rate of 30% of GDP. If India wants to get higher growth of 8% per annum, savings rate has to be much higher.
Domestic savings play a critical role in augmenting capital accumulation and contributing to achieve and sustain high economic growth. Studies show the determinants of savings are GDP, dependency ratio, inflation, price stability, less uncertainty about growth, financial inclusion and quality of employment. These factors have to be strengthened in order to have higher domestic savings.
Reduction in consumption can lead to higher savings. But, consumption is also important for higher growth. There should be a balance between reduction in consumption and increase in savings. Of course, the growth also depends on the incremental capital output ratio (ICOR). If ICOR declines through efficiency and technological change , we need less capital and less savings.
Given states’ role in growth-critical investment, should there be a focus on developing state-level credit ratings?
There is a debate whether Indian states should be rated by credit agencies like corporate rating. This is because despite better fiscal indicators some states have to borrow at higher interest rates. The argument for credit ratings is that it would reduce information asymmetry, encourage fiscal responsibility, better governance, investor confidence and lower borrowing costs for better performers.
But, there are some issues with credit ratings for states. The current state loans are guaranteed by the central government/RBI and this can complicate the ratings.
Niti Aayog released a report on fiscal health index in January 2025 to assess the fiscal performance of Indian states. This type of initiatives can also give information on the fiscal performance of states and can guide in fixing the borrowing costs.
What should be the three most important priorities for policymakers to ensure that growth over the next decade is not only robust, but also inclusive and sustainable?
First, it is difficult to indicate one source of GDP growth. Investment and exports are two engines of growth. Some increase in investment rate including domestic and foreign private investment, efficiency in capital use and enhancement of total factor productivity will boost growth. Rise in savings in the economy is important for higher investments. There are significant opportunities for exports in spite of global uncertainties on trade.
Some other sources of growth are India’s fast growing young work force, urbanisation, rise in human capital and technology, fast growing digital technology including AI. One sector which can transform India is education and skilling which is being pushed by the government.
Second, the 2047 goal is not just growth but also includes inclusive and sustainable growth. Creation of quantity and quality of employment is the most important element of inclusive growth. Structural transformation from agriculture to industry and services over time will increase quality of employment further. Some studies have shown that investing in labour intensive manufacturing and services and rise in formal skilling can raise employment quantity and quality significantly. Recently announced employment linked incentive (ELI) scheme will also boost jobs.
Third, on sustainability, India’s vision is to have a balance in achieving higher growth along with low-carbon emissions and environmental sustainability. It is known that India’s climate efforts are anchored in its commitment to achieve net zero emissions by 2070. Another important initiative by the Prime Minister of India is Life Style for Environment (LiFE) which is a powerful one for achieving sustainable development.
In achieving higher growth which is inclusive and sustainable, states play an important role. It is a healthy sign that states are competing by announcing goals on GDP and GDP per capita. Many studies have shown that improving ‘state capacity’ and governance is important in raising incomes of people and delivering public services like education and health. Similarly, decentralization of resources to Panchayats and Municipal Councils is needed.