

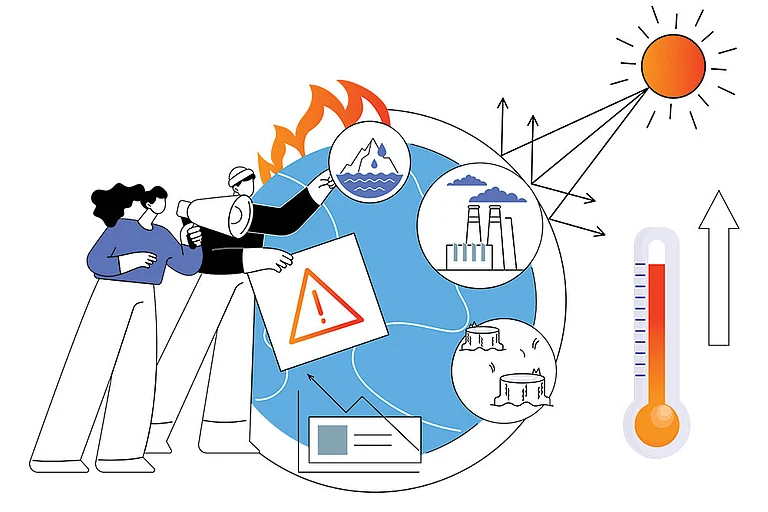
Extreme heat is hurting productivity, incomes and economic output, increasing financial risks for banks.
Agriculture, livestock and heat-exposed workers face higher stress, potentially weakening loan repayment capacity.
Banks can manage the risk through climate-sensitive lending, portfolio diversification, heat insurance and better forecasting.
Extreme heat events, which are becoming increasingly intense and longer, are causing declines in productivity and work efficiency, reduced food production, increased operating costs, and more.
According to a World Bank report, heat exposure will cost 4.5% of India’s GDP by 2030 due to reduced labour output from extreme heat events. A study by Lancet Countdown suggests that the consequences of heat waves led to a loss of earnings of up to $194 billion and 247 billion labour hours in 2024.
1 September 2026
Get the latest issue of Outlook Business
Pricing Heat Risk
The financial sector is affected by extreme heat stress through multiple transmission channels. Extreme heat can lower employee productivity, weaken debt-collection efficiency, and increase operational expenditures due to higher cooling and related energy requirements; these are direct manifestations of heat stress on bank performance.
On the other hand, heat affects banks indirectly by reducing borrowers' productivity and profitability. Extreme weather may also force temporary business shutdowns, leading to unemployment and higher defaults. For businesses not directly exposed to extreme heat, there may still be spillover effects from disruptions in local demand and supply chains. These pressures ultimately transfer to banks and financial institutions through delayed repayments, deteriorating asset quality, and rising portfolio stress.
Advertisement
The impact of rising heat on the banking system is evident globally. Evidence from across Asia, Africa, Europe, North America and Latin America regions suggests that heat affects banking through multiple channels. For example, banks in Germany operating in heat-affected regions report lower returns on assets than comparable banks in less-affected regions. Similarly, rising temperatures are closely associated with higher credit risk, deteriorating asset quality, and increased loan delinquency in other countries.
Indian banks exhibit a similar heat impact. Climate anomalies, including excessive heat, significantly increase credit and liquidity risks. Nationalised banks appear to be more concerned about climate-related credit risks, given their greater presence in sectors sensitive to weather conditions. Moreover, heat-exposed labourers constituted approximately 75% of the labour force in India. Rising temperatures and heat exposure can erode borrowers' incomes, thereby reducing borrowers' loan repayment capacity and straining banks' asset quality.
Advertisement

Agriculture, Livestock Exposure
India is an agrarian economy and ranks among the top five countries globally for agricultural heat stress. According to the UN ESCAP report, the agriculture sector is the hardest hit, accounting for almost 65 per cent of all economic damage from heat due to lower harvest yields and reduced animal productivity. The report mentions that wheat yields in northern India were reduced by 10% to 20% in 2022 due to heat waves, prompting export bans. Furthermore, reduced milk production and increased livestock deaths due to extreme heat also affect borrowers’ ability to repay loans.
Managing Portfolio Risk
In response to rising stress, banks in various countries are adopting multiple measures: tightening credit, requiring higher collateral and reducing deployment to climate-vulnerable regions. For example, banks in the United States are reducing lending in areas that frequently experience extreme heat, particularly in non-core regions where they lack a physical presence.
This means banks, especially geographically diverse banks, are actively adjusting their portfolio risk by integrating climatic conditions into their lending decisions. Besides, Investment in climate risk–monitoring systems can improve banks’ capacity to evaluate heat exposure and price their services accordingly. Banks can calibrate core capital buffers for Indian banks to enhance resilience, given their significant exposure to heat-exposed regions and sectors. Geographical and sectoral diversification of the portfolio can also reduce banks’ exposure to heat-affected regions and industries.
Mitigating Impact
Well-funded heat action plans at the State, district, and city levels are essential to effectively manage heat risks. The construction of cooling shelters and water kiosks is a mandatory step, especially in vulnerable sectors, to prevent a drastic decline in productivity. Improved climate predictions, perhaps using machine learning to forecast the ocean–atmospheric interactions responsible for heat waves and timely dissemination of that information to farmers and small businesses by SMS, can reduce income volatility and lessen repayment challenges. A Study by ESCAP suggests that every 1% increase in prediction accuracy increases agricultural yields by 0.34%.
Heat insurance can provide additional stability in repayment capacity and asset quality. Some innovative insurance products have already been launched: for example, the Adrienne Arsht–Rockefeller Foundation, in collaboration with SEWA (Self-Employed Women’s Association), provides parametric insurance to women vendors whenever temperatures exceed 40°C in Gujarat, Maharashtra, and Rajasthan. Such models, if scaled, can reduce borrower stress and, consequently, lower bank credit risk. Public reinsurance pools by organisations, such as the National Bank for Agriculture and Rural Development (NABARD), may help stabilise premiums for parametric insurance products that protect climate-sensitive sectors
The financial sector in India is currently at a crucial juncture. Failing to account for, prepare for, and protect against increased heat risk could gradually turn it into a major source of financial risks.
Labanya is Director at Climate and Sustainability Initiative (CSI) and Visiting Senior Fellow, London School of Economics and Political Science, while Insha is Research Analyst at CSI.


Disclaimer: Views expressed are personal.